
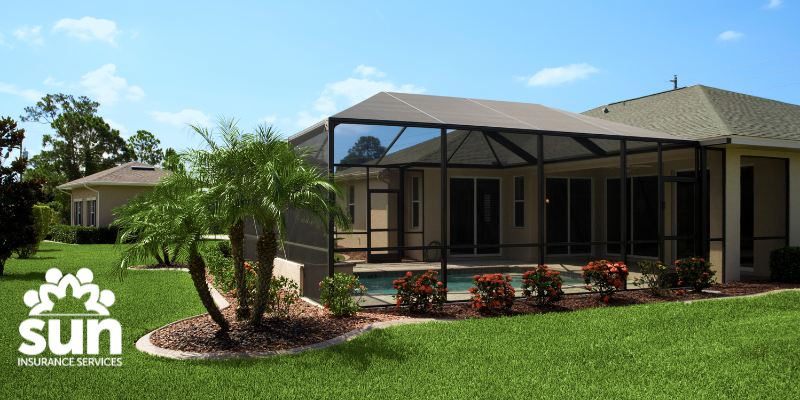
Florida homeowners insurance does not automatically cover a pool cage or screen enclosure after a storm. Some policies limit or exclude these structures, especially for wind or hurricane damage. A separate endorsement may be needed, and coverage for the frame and screening may differ.
Before renewing, buying a home with a pool, or replacing an enclosure, ask for a review of the actual policy and endorsements. A dwelling limit or other-structures limit on the declarations page does not override an exclusion.
What determines whether a pool cage is covered?
The structure’s construction, the cause of damage, and the policy wording determine whether coverage applies. Being attached to the house does not by itself establish coverage.
- Structure: Describe the aluminum frame, screen panels, roof materials, and attachment to the home.
- Cause of loss: Wind, hurricane, falling objects, and flood can receive different treatment.
- Exclusions: Look for wording about screen enclosures, open structures, and aluminum construction.
- Endorsements: Confirm any added coverage, its limit, and what components it includes.
- Settlement: Check the deductible, depreciation, and repair or replacement conditions.
For the rest of the property, review our Florida home insurance options.
Can an endorsement add pool cage coverage?
Some insurers offer a screened-enclosure endorsement, but availability and terms vary. An endorsement is a document that changes the base policy.
The Florida Insurance Consumer Advocate’s endorsement guide explains that some insurers limit or exclude screened enclosures and offer additional hurricane coverage. Ask whether an offered endorsement includes your pool cage, the aluminum frame, screening material, and any attached awning. Do not assume an increase in general other-structures coverage removes a specific exclusion.
Have a pool cage at your Florida home? Contact Kim Osburn for a policy review or call Kim at 407-781-1620. Have your declarations page and enclosure photos available.
Does Citizens cover pool cages?
Citizens states that its homeowners policies do not cover structures constructed to be open to the weather, including the pool-cage examples addressed in its guidance. Do not assume Citizens provides pool cage coverage because it covers the house.
See Citizens’ guidance on pool cages and open structures. Ask the agent to identify the applicable exclusion and check your policy type, edition, and endorsements before relying on coverage.
Does a hurricane deductible apply to every named storm?
No. A storm having a name does not automatically trigger a Florida hurricane deductible. The hurricane definition, applicable timing rules, cause of loss, and policy terms matter.
Review the Florida Department of Financial Services hurricane deductible guide and ask which deductible applies to covered enclosure damage. A deductible is considered only after determining that the damage is covered. An excluded pool cage does not become insured because the homeowner is willing to pay the deductible.
For a percentage deductible, ask for the dollar calculation using the policy’s specified coverage amount. Also confirm whether an enclosure endorsement has its own deductible or conditions.
Will flood insurance pay for a damaged pool cage?
Do not assume it will. Standard homeowners insurance generally excludes flood, and a separate flood policy has its own definition of insured property and exclusions.
Flood insurance is not an automatic replacement for excluded screen-enclosure coverage. Ask specifically whether the enclosure is insured under the proposed flood policy, rather than relying on the fact that the home has flood insurance. Review Florida flood insurance options separately from wind coverage.
How much pool cage coverage should you request?
Use a current repair or replacement estimate and compare it with the coverage actually available. A general percentage of dwelling coverage may not represent the pool cage’s insured limit.
Ask whether the policy pays replacement cost or actual cash value, which generally reflects depreciation. Replacement-cost provisions can still include payment conditions, limits, and deductibles. Confirm whether debris removal, code-related work, screening, and frame replacement are included or limited. Keep estimates, photos, and installation records for future reviews.
What should you do after storm damage?
Report damage promptly, document it when safe, and follow the insurer’s instructions and policy duties. Do not delay reporting while trying to decide coverage yourself.
- Keep people away from unstable framing, sharp metal, and electrical hazards.
- Photograph the enclosure and surrounding damage from a safe position.
- Take reasonable steps to prevent further damage when safe and keep receipts.
- Contact the insurer and preserve relevant evidence for inspection.
- Obtain written repair estimates and keep claim correspondence.
Frequently asked questions
Does Coverage B automatically insure a pool cage?
No. Coverage B generally concerns other structures, but an exclusion or endorsement can change how an enclosure is treated. Check the complete policy rather than treating the other-structures dollar amount as proof of pool cage coverage.
Are the aluminum frame and screens covered the same way?
Not necessarily. The policy may distinguish structural components from screening material or apply different restrictions by cause of damage. Ask the agent to explain both components using the actual endorsement wording.
Can you add coverage after a storm damages the enclosure?
A new endorsement does not retroactively insure an existing loss. Insurer approval, effective dates, underwriting, and any binding restrictions apply. Review coverage before storm season or replacement work rather than waiting until damage occurs.
Review the enclosure before your next renewal
Sun Insurance Services is a family-owned independent agency based in Orlando and founded in 2003. Contact Kim Osburn or call 407-781-1620 to review the home address, current policy, enclosure construction, and replacement estimate.
Last updated: November 10, 2026. Coverage depends on the issued policy, endorsements, limits, deductibles, and exclusions.
Usually takes about 2 minutes